Case Studies
Panama Permanent Residence for Building a Base Outside the US
“I wanted a permanent base outside the US without giving up my American business or citizenship. Panama gave me a home I could actually use, while my tax advisers built a compliant strategy around where I lived, travelled, and performed my work.”
 Share
 Telegram
 Facebook
 LinkedIn
 X

 Save
Why the client wanted a permanent base outside the US
Andrew had worked as an independent cloud infrastructure consultant for more than 10 years. Most of his clients were technology companies in the US, Canada, and Europe, and he could perform the majority of his work remotely.
His business had become increasingly international, but his personal structure had not. He still relied on the US as his only
He set 3 objectives:
- Establish a permanent home and legal status outside the US.
- Diversify part of his capital into property in another jurisdiction.
- Review whether spending substantially more time abroad could legally reduce his US federal income tax through the Foreign Earned Income Exclusion, or FEIE.
Tax planning was one of the factors Andrew considered when comparing residence options, but no immigration status could automatically reduce his US taxes. Once Panama emerged as the preferred option, his advisers assessed the Panamanian residence, US tax position, and potential local tax obligations separately.
Comparison of residence options
Andrew initially considered several routes suited to remote professionals. Passportivity compared them not only by cost, but also by duration of status, residence requirements, investment structure, and how well each option fitted Andrew’s plan to create a permanent base rather than spend a year or two abroad.
Residence options Andrew compared
| Option | What Andrew considered | Fit for his strategy |
|---|---|---|
| Portugal Digital Nomad residence | More | |
| Costa Rica Digital Nomad programme | Good | |
| Panama Qualified Investor | Direct permanent residence through investment, property ownership, and no requirement to live in Panama continuously to maintain the status | ⭐ Best fit — provided a permanent base and a tangible asset |
Portugal’s
Costa Rica’s Digital Nomad programme, meanwhile, generally grants a
Panama gave Andrew something different: permanent residence from the outset through a qualifying investment. The Qualified Investor programme permits real estate investment as one of the routes to permanent status.
Why Panama permanent residence matched the client’s plans
Panama combined the immigration status Andrew wanted with the possibility of purchasing an apartment he could use as his own base.
1. Permanent residence through property investment
Andrew preferred property to securities or a
He selected a new
When Andrew started the property purchase in 2024, the minimum real estate investment under the Qualified Investor programme was $300,000. This threshold was initially due to apply until October 15th, 2024, but Decree No. 193, adopted on that date, retained the $300,000 minimum. Andrew’s $315,000 apartment therefore met the requirement when his residence application was filed later that month.
The rules changed again in September 2026. Under the current framework, qualifying new
2. Long-term base outside the US
Andrew did not want a temporary digital nomad status that had to be replaced after one or two years. Panama granted him permanent residence. The status is indefinite, although the residence card itself requires periodic renewal. The qualifying investment must generally be maintained for the required programme period.
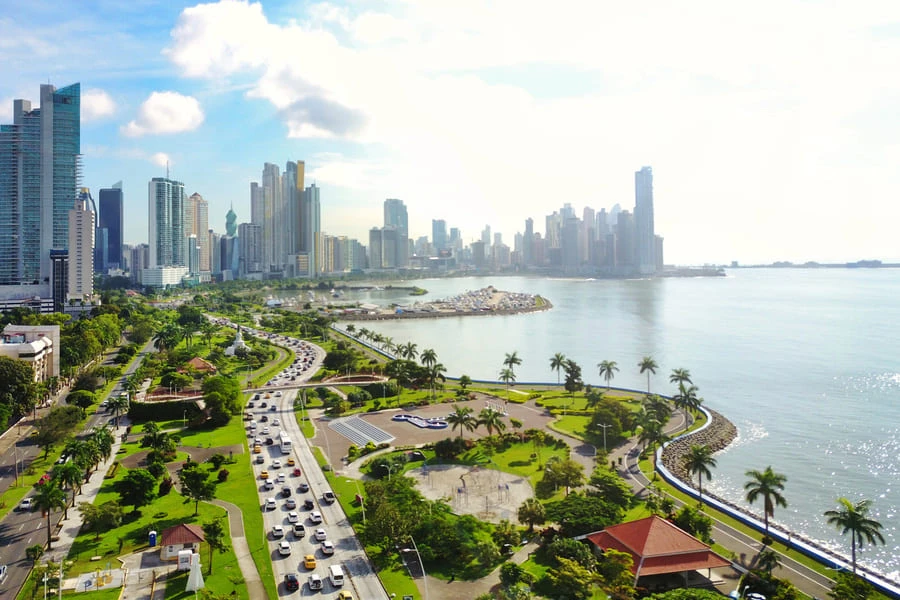
The apartment also gave Andrew a fixed address between business trips. He continued working with American clients but started using Panama City as his regular base for travel across Latin America and Europe.
3. Residence became one part of US tax planning
Andrew retained his citizenship and therefore continued to file US tax returns. His residence card did not exempt him from American tax. Instead, his tax adviser assessed whether his new lifestyle could meet the separate requirements for the Foreign Earned Income Exclusion.
To use FEIE, a taxpayer must have a tax home in a foreign country and meet either the bona fide residence test or the physical presence test. Serviço de Receita Interna Based on Andrew’s working arrangements, his adviser chose the physical presence test.
 Elena Garnitsarik
Head of the Legal Department
4. Why the 330-day rule mattered
Andrew travelled frequently, so the physical presence test fitted his situation better than building the strategy around residence in one foreign country for an entire tax year. The test requires physical presence in one or more foreign countries for at least 330 full days during a period of 12 consecutive months. The days do not have to be consecutive or spent in the same foreign country. During 2025, Andrew spent 334 full days outside the US.
His year included time in:
- Panama, where he maintained his apartment and regular base;
- Mexico and Colombia for client projects;
- Spain and Portugal for work and personal travel;
- US for several short visits totalling fewer than 31 days.
His US tax adviser also reviewed whether the facts supported a foreign tax home. The Panama residence card helped document the wider move abroad, but it was not sufficient on its own.
5. Panama’s territorial tax system required separate analysis
Panama generally applies a territorial principle: individuals are taxed on
For professional services, where the activity is performed matters. Panama’s tax authority states that income from activities performed within Panamanian territory may be subject to income tax regardless of the recipient’s nationality or residence.
Andrew’s tax adviser in Panama therefore separated his consulting income according to where the work was actually performed. Income from services carried out abroad could fall outside local income tax under the territorial principle, while work physically performed in the country required a separate assessment. This distinction became an important part of his travel and tax records.
6. Property diversified part of Andrew’s assets outside the US
Before the project, most of Andrew’s assets consisted of US brokerage investments, retirement accounts, and cash. The $315,000 Panama apartment added real estate in another jurisdiction.
Andrew did not purchase the property primarily for speculative returns. He intended to use it as a home base while satisfying the investment requirement for permanent residence.
After the mandatory
7. Permanent residence did not require giving up US citizenship
Andrew had no plans to renounce his citizenship. The two statuses served different purposes: his US passport remained proof of nationality, while permanent residence in Panama gave him an indefinite right to reside in another country.
He also remained subject to US filing requirements. FEIE potentially reduces federal income tax on qualifying foreign earned income, but it does not end US tax residency or eliminate all US taxes.
For a
How Passportivity coordinated the residence and tax strategy
Passportivity handled the immigration and property components of the project while keeping specialist tax advice separate.
The team first established what Andrew actually wanted the Panama status to achieve. Passportivity then:
- compared permanent and temporary residence options;
- conducted Preliminary Due Diligence;
- helped select the qualifying property route;
- coordinated property Legal Due Diligence;
- prepared the residence application;
- documented the source of funds used for the purchase;
- coordinated the timeline with Andrew’s US CPA and Panamanian tax adviser.
Passportivity did not promise a particular tax saving.
Andrew’s accountants determined separately whether he met FEIE requirements, how much income qualified, and which part of his professional income required.
Buying an apartment in Panama
Andrew wanted a property he could use himself rather than an investment unit chosen only to meet the programme threshold.
Property selection
Passportivity’s real estate specialists shortlisted apartments in Panama City with three priorities:
- purchase price comfortably above the qualifying threshold;
- completed or
near-completed building; - convenient location for Andrew’s
day-to-day life and business travel.
Andrew selected a 96 m²,
Legal Due Diligence
Before Andrew transferred the purchase funds, local specialists reviewed the property documents. The check covered ownership, existing liens, developer documentation, property registration, and whether the apartment met the requirements for the residence application. No issues preventing the purchase were identified.
Purchase and ownership registration
Andrew transferred the purchase funds from his US account. The transaction was completed and ownership was registered before the permanent residence application was filed, allowing the property documents to serve as evidence of the qualifying investment.
How Andrew qualified for FEIE
Andrew’s tax strategy was implemented after he established his base abroad. Permanent residence was useful evidence of a genuine international move, but FEIE eligibility depended on US tax rules rather than Panamanian immigration law.
Establishing a tax home abroad
Andrew moved his regular home abroad and used his Panama apartment as his stable residential base.
His US tax adviser reviewed his business arrangements, travel pattern, home, and personal connections before determining that his circumstances supported a foreign tax home for the relevant period.
Meeting the physical presence test
Andrew kept a detailed travel calendar and supporting flight and immigration records. During the qualifying
Determining qualifying foreign earned income
FEIE applies to earned income from personal services performed in a foreign country. The source is generally determined by where the work is physically performed, not where the client is incorporated or where payment is received.
Andrew’s accountant therefore separated work performed while he was abroad from work done during his short visits to the US, and earned income from
For the 2025 tax year, the maximum FEIE was $130,000 per qualifying individual. Andrew’s adviser determined the actual amount he was entitled to exclude based on his qualifying foreign earned income and business expenses.
Filing for FEIE
Andrew continued filing a US federal tax return. His accountant elected the Foreign Earned Income Exclusion using Form 2555. The exclusion reduced the amount of qualifying earned income subject to US federal income tax. It did not remove all filing requirements,
Expenses on obtaining Panama permanent residence
Andrew spent approximately $329,200 on the property and residence project, excluding Passportivity professional services.
The apartment remained Andrew’s asset; the $315,000 was not a
Andrew’s expenses on Panama permanent residence
| Expense | Amount | What it covered |
|---|---|---|
| Apartment purchase | $315,000 | 96 m² apartment in Costa del Este |
| National Migration fee | $5,000 | Government residence fee |
| National Treasury fee | $5,000 | Government payment under the investment route |
| Property registration and document expenses | ≈ $4,200 | Notary, registration, apostilles, translations, medical certificate and related documents |
| Total | ≈ $329,200 | Excluding Passportivity professional services |
How Andrew obtained Panama permanent residence
Passportivity started Andrew’s case on August 12th, 2024. He received his permanent residence card on December 20th, 2024. The entire process took 4 months and 8 days, including property selection and purchase.
The programme allows much of the preparation and filing to be handled through a Panamanian lawyer, while the investor travels to Panama for biometrics and collection of residence documents.
-
2 business days, August 12th to 13th, 2024
Preliminary Due Diligence
Passportivity checked Andrew’s background, source of income, previous immigration history, and information available in international databases. No issues preventing the application were identified.
-
2 weeks, August 14th to 27th, 2024
Residence strategy
Passportivity compared Panama with other options Andrew had considered and separated the immigration project from his future US and Panama tax planning. Andrew chose the Qualified Investor route.
-
3 weeks, August 28th to September 17th, 2024
Property selection
Specialists shortlisted qualifying new apartments in Panama City. Andrew selected a 96 m² apartment in Costa del Este for $315,000.
-
2 weeks, September 18th to October 1st, 2024
Due Diligence
Local specialists reviewed ownership documents, developer records, encumbrances, and the property’s suitability for the residence application.
-
3 weeks, October 2nd to 25th, 2024
Purchase and ownership registration
Andrew transferred the funds from his US account, completed the property purchase, and registered ownership in Panama.
-
1 day, October 28th, 2024
Permanent residence application
The application and evidence of Andrew’s qualifying investment were submitted to the National Migration Service through his Panamanian representative.
-
6 weeks, October 29th to December 10th, 2024
Application processing
The authorities reviewed Andrew’s documents, source of investment funds, and evidence of the property purchase.
-
8 business days, December 11th to 20th, 2024
Biometrics and permanent residence card
Andrew travelled to Panama, completed the required
in-person formalities, submitted biometrics, and received his permanent resident card on December 20th.
Result: permanent residence and an international base
Andrew did not move his consulting business out of the US. Instead, he added a second permanent base to his existing structure.
Residence. Andrew obtained indefinite permanent status in Panama and a home he could use between international trips.
Business. Working remotely from abroad allowed him to keep existing US clients while spending more time developing contacts in Latin America and Europe.
Assets. The $315,000 apartment added property outside the US to Andrew’s portfolio and became his regular international base.
The biggest change was not just the tax calculation. I stopped treating every month abroad as temporary. I now have permanent status, my own home outside the US, and a structure that lets me plan where I work and travel much more deliberately.
Andrew Collins
Independent IT consultant
Taxes. The residence itself changed nothing in Andrew’s US filing position — the tax outcome depended on separate tests. After he met the
In Panama, his advisers applied the country’s territorial rules according to where his services were actually performed, rather than assuming that payments from foreign clients were automatically exempt.
Schedule a meeting
Help with the choice
Passportivity experts will analyse your situation and offer the most suitable solution.